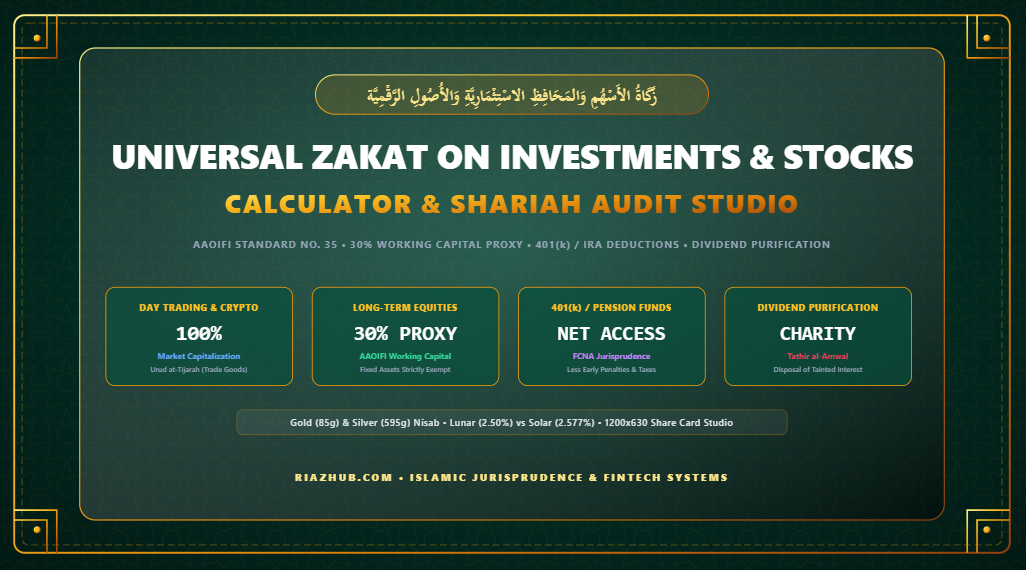
A comprehensive, scholarly analysis on calculating Zakat across modern financial instruments: day-trading equities, index funds, long-term dividend portfolios via the 30% working capital proxy method, 401(k) / IRA retirement accounts, Web3 crypto assets, and dividend purification protocols.
1. The Modern Investment Dilemma: Why Classical Rulings Require Contextual Application
In classical Islamic jurisprudence, wealth subject to Zakat fell into easily identifiable tangible categories: gold and silver bullion (الأثمان), livestock (الأنعام), agricultural harvests (الحبوب والثمار), and physical trade inventory (عروض التجارة).
Today, over 80% of global Muslim wealth is invested in intangible, complex financial assets: fractional shares in multinational corporations, index funds (ETFs), employer-sponsored retirement plans like 401(k)s and IRAs, liquid stablecoins, and decentralized digital currencies.
When a modern Muslim attempts to fulfill their third pillar of Islam, they frequently encounter two contradictory and inaccurate extremes:
- The Naive 100% Market Value Rule: Applying a flat 2.5% to the entire gross portfolio value of long-term equities, forcing the investor to pay Zakat on industrial factories, proprietary patents, and commercial real estate owned by the corporation—assets that are unanimously exempt from Zakat under classical Shariah.
- The “Zero Zakat” Dividend-Only Myth: Mistakenly assuming that because shares are not physical currency, Zakat is only due on cash dividend distributions, ignoring the company’s circulating cash reserves, short-term receivables, and finished inventory.
To bridge this gap, international councils including the International Islamic Fiqh Academy and the Accounting and Auditing Organization for Islamic Financial Institutions (AAOIFI) issued foundational standards: specifically AAOIFI Shari’ah Standard No. 35 (Zakat on Shares). You can instantly implement these institutional standards via the Universal Zakat on Investments & Stocks Studio.
2. Mudharib vs. Mustathmir: The Dual Classification of Equities
Under Islamic legal principles, the intent of the shareholder (النية) governs the legal status of the equity asset:
Legal Status: Trade Merchandise (عروض التجارة).
Intent: Rapid capital gains, arbitrage, or short-term swing trading.
Zakatable Base: 100% of current market value on your annual Hawl date.
Legal Status: Proportional Business Partnership (الشركة).
Intent: Dividend yield, long-term capital compounding, and ownership.
Zakatable Base: Net Zakatable Working Capital only (Exempting fixed corporate assets).
“If the owner acquired shares with the intention of reselling them to benefit from price fluctuations, he must evaluate them at their market value on the date Zakat falls due and pay 2.5% on their full value, exactly like trade merchandise.”
OIC International Islamic Fiqh Academy, Resolution No. 120 (13/3)
If you engage in day trading or swing trading equities or crypto, enter your market values directly into Category 1 of the RiazHub Investment Zakat Calculator, which evaluates them at 100% market capitalization.
3. Why Corporate Fixed Assets Are Exempt: The 25%–30% Working Capital Proxy
Why should a long-term shareholder NOT pay Zakat on 100% of their share value?
In Islamic jurisprudence, capital equipment used in the production process (أدوات الإنتاج / العوامل) such as an airline’s airplanes, a tech company’s data centers, a carmaker’s automated assembly lines, and corporate office complexes are strictly exempt from Zakat. The Prophet Muhammad (ﷺ) established:
“There is no charity due from a Muslim upon his slave or his horse [the productive tools and means of transport].”
Sahih Bukhari 1464, Sahih Muslim 982
When you purchase a share in Apple, Microsoft, or an S&P 500 ETF, you become a fractional owner of both its fixed productive assets (exempt) and its circulating liquid assets (zakatable).
How Working Capital Is Calculated
A corporation’s zakatable pool consists of its Net Working Capital:
Zakatable Corporate Capital = (Cash + Marketable Securities + Inventory + Trade Receivables) – (Short-Term Payables & Immediate Liabilities)
The Empirical Origin of the 30% Proxy Rule
For individual retail investors holding mutual funds, ETFs, or portfolios of dozens of international stocks, inspecting hundreds of quarterly balance sheets is impossible.
Consequently, leading contemporary Islamic financial jurists—including Justice Mufti Taqi Usmani, Dr. Ali Al-Qurradaghi, and committees at AAOIFI conducted empirical financial audits of global Shariah-compliant indices (such as the Dow Jones Islamic Index and S&P Shariah Index).
Their findings demonstrated that across diversified equity portfolios, net zakatable liquid assets consistently average between 20% and 30% of market capitalization.
| Calculation Methodology | Applied Ratio | Scholarly Basis | Best Suited For |
|---|---|---|---|
| Standard AAOIFI Proxy | 30% of Market Value | AAOIFI Standard 35 Consensus | Diversified Index Funds, Tech ETFs & Blue Chips |
| Conservative Rule-of-Thumb | 25% of Market Value | Contemporary Middle Eastern Fatwa Boards | Industrial & Capital-Intensive Sectors |
| Precautionary Full Value | 100% of Market Value | Strict Precautionary Position | Active traders or risk-averse individuals |
You can toggle between the 30% AAOIFI standard, the 25% conservative ratio, or a custom percentage with a single click in the online investment Zakat screener.
4. Retirement & Pension Accounts: 401(k), Traditional IRA & Superannuation
Calculating Zakat on employer-sponsored retirement plans is one of the most frequently misunderstood topics in modern Islamic finance. In countries like the United States, Canada, the UK, and Australia, funds placed into 401(k), 403(b), Traditional IRA, RRSP, or Superannuation accounts cannot be withdrawn freely prior to retirement age (e.g., age 59½) without triggering heavy penalties.
The Fiqh Principle of Al-Milkiyyah at-Tammah (Complete Ownership)
Classical jurists established that Zakat is only obligatory upon wealth over which the owner exercises Al-Milkiyyah at-Tammah: complete, unencumbered ownership coupled with the legal capacity to access and liquidate the asset.
If you have $100,000 in a traditional 401(k) and attempted to withdraw it today, you would never receive $100,000. Instead:
- The government levies an immediate 10% early withdrawal penalty.
- Federal and state authorities deduct mandatory estimated income taxes (typically between 20% and 25%).
Therefore, only the net accessible liquidation value (typically ~65% to 70% of the gross balance) constitutes true owned capital under the resolution of the Fiqh Council of North America (FCNA).
Two Scholarly Approaches to Retirement Zakat
- Immediate Annual Net Assessment (Recommended): You deduct the early penalty (10%) and estimated tax liability (20%), and then pay Zakat annually on the accessible net balance. If the underlying fund is held as long-term equities, you can further apply the 30% AAOIFI proxy to that net accessible sum.
- Deferred Liquidation Assessment (Alternative): Some classical scholars hold that because retirement funds are restricted, no Zakat is due until you reach retirement age and actually liquidate the funds, upon which you pay Zakat for one single Hawl.
The RiazHub Zakat on Investments Studio features an automated FCNA deduction protocol: simply enter your gross 401(k) balance, and the system instantly subtracts statutory penalties and taxes before computing your exact Zakat obligation.
5. Cryptocurrency & Web3 Digital Assets: BTC, ETH, Altcoins & Stablecoins
Digital assets represent a legitimate modern form of circulating wealth (المال المتمول). Shariah boards and contemporary jurists categorize crypto holdings based on their functional economic role:
- Spot Trading Tokens (Bitcoin, Ethereum, Solana, Altcoins): Acquired with the expectation of market appreciation or active trading. Treated as trade merchandise at 100% current market capitalization.
- Stablecoins (USDT, USDC, DAI): Pegged to fiat currency reserves. Functionally equivalent to cash (الأثمان) and zakatable at 100% face value.
- Staking Rewards & Yield Farming: Any accrued staking yields that are accessible on your annual Hawl date are treated as realized cash gains and added directly to your zakatable base.
6. Dividend Purification Protocol (تطهير الأرباح)
Even in certified Shariah-compliant stock screeners (such as AAOIFI, S&P Shariah, or FTSE Islamic indices), companies are permitted to hold a small portion of interest-bearing debt or cash deposits—provided non-permissible interest income does not exceed 5% of gross revenue.
While the underlying stock remains permissible to own, the investor is spiritually obligated to purify their dividends:
Dividend Purification Amount = Annual Cash Dividends Received × Non-Permissible Revenue Ratio %
Crucial Fiqh Rule: Purified dividend money must be given away to public humanitarian causes or the poor without expecting spiritual Zakat reward. It is a disposal of tainted funds (التخلص من المال الخبيث), not Zakat itself. The RiazHub calculator computes this purification amount separately from your Zakat due.
7. Dual Calendar Accounting: Lunar Hawl (2.50%) vs. Solar Fiscal Year (2.577%)
The standard Islamic Hawl is established on 12 lunar months (354 days) at the rate of 2.50% (one-fortieth):
“In silver, for every forty dirhams, one dirham is due.”
Sunan Abi Dawud 1573
However, almost all global brokerage firms, retirement accounts, and corporate tax returns operate on the Gregorian solar calendar (365.25 days). Because the solar year is 11 days longer than the lunar year, paying only 2.50% on a solar calendar results in underpaying Zakat over time.
To resolve this mathematical discrepancy, AAOIFI Shari’ah Standard No. 35 stipulates the exact solar-adjusted Zakat rate:
Solar Fiscal Rate = 2.50% × (365.25 days / 354 days) = 2.577%
When utilizing our Universal Investment Zakat Studio, you can toggle between the 2.50% lunar standard and the 2.577% solar fiscal rate with instant automatic recalculation.
8. Real-World Case Study: Auditing a Tech Professional’s Portfolio
Let us examine a concrete audit for Tariq, a software engineer residing in the United States with the following diversified holdings on his annual Hawl date:
| Asset Description | Gross Value | Applied Fiqh Treatment | Net Zakatable Base |
|---|---|---|---|
| Day-Trading Tech Stocks | $25,000 | 100% Market Value (Trade Merchandise) | $25,000 |
| Long-Term S&P 500 Islamic ETF | $100,000 | 30% AAOIFI Proxy (Working Capital) | $30,000 |
| Employer 401(k) Retirement Plan | $120,000 | Net Liquidity (10% penalty + 20% tax) × 30% Proxy | $25,200 |
| Bitcoin & Ethereum (Crypto) | $15,000 | 100% Market Value (Digital Currency) | $15,000 |
| Liquid Stablecoins (USDC) | $5,000 | 100% Face Value (Cash Equivalent) | $5,000 |
| Brokerage Margin Loan (Debt Due) | ($8,000) | Immediate Deductible Liability | -$8,000 |
| TOTALS | $265,000 Gross | Nisab Status: Exceeds Threshold | $92,200 Net Base |
Audit Results
- Gross Portfolio Value: $265,000
- Corporate Fixed Assets Exempted: $70,000 (from passive ETF) + $58,800 (from 401k) = $128,800 saved from incorrect taxation
- Net Zakatable Base: $92,200
- Zakat Due (Lunar 2.50%): $2,305.00
- Zakat Due (Solar 2.577%): $2,376.00
- Purification Charity (on $2,000 dividends @ 3% tainted): $60.00
Notice that Tariq’s Zakat obligation on a $265,000 portfolio is only $2,305—rather than the staggering $6,625 he would have mistakenly paid under a naive 100% flat assessment! You can verify your exact figures right now using the RiazHub Investment Zakat Calculator.
9. Frequently Asked Questions (FAQ)
Are unvested Restricted Stock Units (RSUs) zakatable?
No. Unvested RSUs and unexercised employee stock options lack the essential Shariah condition of complete ownership (الملكية التامة). You cannot sell, transfer, or gift them until they vest. Once vested and deposited into your brokerage account, they become fully owned and zakatable on your subsequent Hawl.
What is the difference between a Traditional IRA and a Roth IRA?
With a Traditional IRA, early withdrawals incur both a 10% penalty and standard income tax liabilities; both deductions should be subtracted when calculating your accessible net balance. With a Roth IRA, your original contributions were already taxed, so contributions can be withdrawn penalty-free and tax-free at any time meaning only your capital gains growth would be subject to penalties upon early withdrawal.
Should I use the Gold Nisab or the Silver Nisab for stocks?
Classical Hanafi jurists traditionally recommended the Silver Nisab (595g) because historically it triggered Zakat earlier to support the poor. However, due to the severe historical depreciation of silver relative to gold, contemporary scholars and the Fiqh Council of North America recommend the Gold Nisab (85 grams of 24K gold) for modern investment portfolios, as gold preserves true purchasing power. Our investment Zakat calculator supports instant switching between both standards.
Is my confidential financial information saved on your servers?
Strictly no. The Zakat on Investments Calculator operates entirely inside your local browser memory using client-side JavaScript. Zero portfolio holdings, balances, or IP addresses are transmitted across the internet.
Universal Zakat on Investments, Stocks, Crypto & Retirement Studio
An institutional-grade portfolio Zakat auditor for active day traders, passive dividend investors, Web3 holders, and retirement accounts. Features dynamic working capital proxies, dividend purification algorithms, and dual lunar/solar Hawl reconciliation.
Investment Zakat Audit Ledger
| Asset Category | Gross Value | Fiqh Treatment | Net Zakatable |
|---|
Portfolio Working Capital & Exemption Analysis
Illustrates why Muslims do not pay Zakat on factory machinery, industrial real estate, or corporate fixed assets.
Asset Class Diversification Mix:
Islamic Jurisprudence of Modern Investments
1. The Dual Classification of Equities: Mudharib vs. Mustathmir
In classical jurisprudence, wealth is zakatable either as cash (Athman), trade merchandise ('Urud at-Tijarah), or agricultural/livestock produce. The International Islamic Fiqh Academy (Resolution No. 120) and AAOIFI Standard No. 35 classify shares based on shareholder intent:
Active Day Trader (المضارب): Purchases shares with the intent of liquidating for capital gains. Valued at 100% current market price, exactly like trade merchandise.
Passive Long-Term Investor (المستثمر طويل الأجل): Holds shares for regular dividend yields and corporate partnership. Only the company's net zakatable liquid assets (cash, inventory, accounts receivable minus short-term payables) are subject to Zakat.
2. The Empirical Basis for the 25%–30% Working Capital Proxy
When investors hold broad index funds (e.g. S&P 500, MSCI World Islamic) or diversified portfolios, acquiring audited balance sheets for hundreds of corporations is practically impossible. Empirical financial audits conducted by AAOIFI scholars demonstrated that the net working capital of listed corporations typically averages between 20% and 30% of their total market capitalization. Jurists therefore endorse applying a standard 30% proxy ratio (or 25% in conservative jurisdictions) to long-term equity holdings.
3. Retirement Accounts (401k, 403b, IRA, Superannuation)
According to the Fiqh Council of North America (FCNA) and contemporary authorities, the classical condition of Al-Milkiyyah at-Tammah (Complete, Unrestricted Ownership) requires the owner to have unimpeded access to dispose of the wealth. Since early withdrawal incurs mandatory statutory penalties (typically 10%) and immediate income taxation (20%–25%), only the net residual balance after deducting these immediate obligations is legally considered owned capital.
4. Dividend Purification Protocol (تطهير الأرباح)
Even Shariah-compliant equity indices permit companies to hold up to 5% non-permissible interest income. Investors are obligated to purify their dividends by calculating the tainted percentage and distributing that exact sum to public charity without claiming spiritual Zakat reward.
High-resolution 1200x630 balance sheet card optimized for WhatsApp, Telegram, Twitter/X, and corporate records.
Comprehensive Investment Fiqh Reference
Authoritative jurisprudence based on AAOIFI, OIC Islamic Fiqh Academy, and global Fatwa councils.