How to Calculate Zakat on Business Assets & Commercial Wealth: The Comprehensive Fiqh and AAOIFI Working Capital Guide
For Muslim entrepreneurs, store owners, corporate executives, and e-commerce merchants, fulfilling the obligation of Zakat on business assets (زَكَاةُ عُرُوضِ التِّجَارَة Zakat Urud at-Tijarah) represents one of the most critical pillars of commercial ethics in Islam. Far from being a mere voluntary donation, Zakat is a mandatory annual levy designed to purify wealth, stimulate the ethical circulation of liquidity, and safeguard economic equilibrium.
However, in contemporary business accounting, calculating commercial Zakat often causes considerable confusion. Business owners frequently wonder:
- Should inventory be evaluated at its historical cost, current wholesale liquidation value, or anticipated retail price?
- Are delivery vehicles, warehouse buildings, and manufacturing equipment taxable?
- How should supplier invoices (ذمم دائنة) and long-term bank financing be deducted?
- What happens if your corporate accounts operate on a 365-day Gregorian solar calendar instead of the 354-day Islamic lunar year?
This exhaustive guide details the classical rulings across the four major Sunni schools of jurisprudence (Hanafi, Maliki, Shafi’i, and Hanbali), reconciles them with contemporary international accounting standards (AAOIFI Shari’ah Standard No. 35), and demonstrates how to audit your enterprise accurately.
1. Jurisprudential Foundations: Is Zakat Obligatory on Commercial Merchandise?
The obligation of Zakat on trade merchandise is established by consensus (إجماع) among the Sahabah and the classical Jurists. Allah ﷻ states in the Holy Quran:
“O you who have believed, spend from the good things which you have earned and from that which We have produced for you from the earth…”
Surah Al-Baqarah (2:267)
Imam Mujahid, the illustrious student of Abdullah ibn Abbas (رضي الله عنه), explained that this verse was revealed specifically in reference to commercial goods prepared for trade. Furthermore, Abu Dawud recorded in his Sunan from the companion Samurah ibn Jundub (رضي الله عنه):
“The Messenger of Allah ﷺ commanded us to pay Zakat on everything that we prepared for sale.”
Sunan Abi Dawud (Book of Zakat, Hadith 1562)
Whenever the Hawl (one full Islamic lunar year of ownership) elapsed, the second Caliph, Umar ibn al-Khattab (رضي الله عنه), instructed commercial traders: “Appraise your goods, calculate your liquid dirhams and dinars, and pay the Zakat due upon them.”
2. The Core Commercial Zakat Formula: The Working Capital Method
Contemporary Islamic financial institutions, including the Accounting and Auditing Organization for Islamic Financial Institutions (AAOIFI), recognize two equivalent methodologies for computing corporate Zakat:
- The Net Working Capital / Current Assets Method (طريقة صافي الأصول المتداولة): Best suited for sole proprietorships, retail shops, wholesale distributors, and digital e-commerce merchants.
- The Adjusted Net Worth Method (طريقة رأس المال العامل المعدل): Typically applied to audited public corporations and large conglomerates.
Both formulas yield identical mathematical results. Under the Net Working Capital approach, the formula is:
The Universal Commercial Zakat Equation
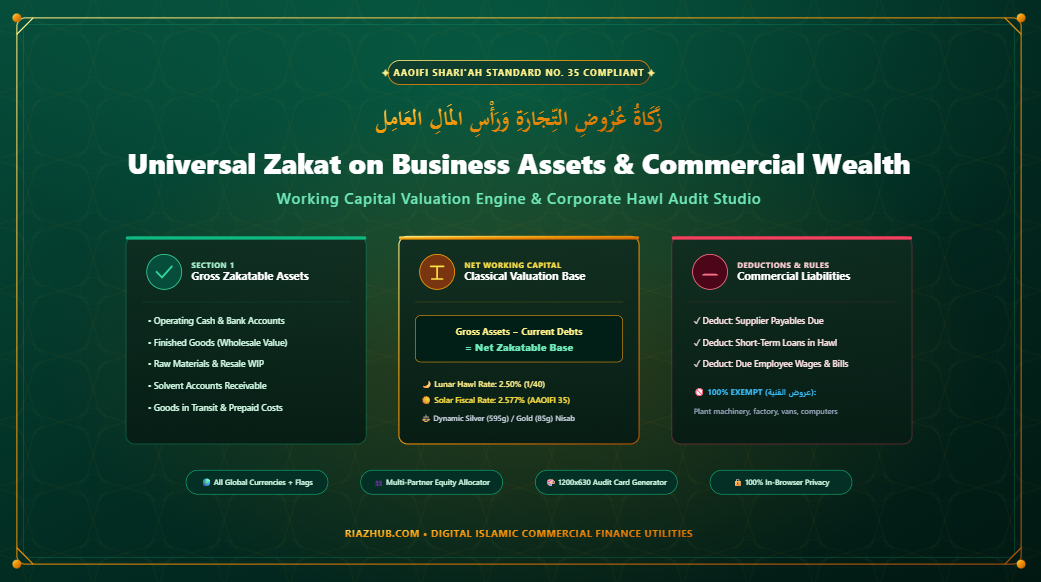
Gross Zakatable Working Assets = Liquid Operating Cash + Finished Goods Inventory (Wholesale Value) + Raw Materials for Resale + Solvent Accounts Receivable + Prepaid Operational Expenses
Deductible Commercial Liabilities = Trade Accounts Payable to Suppliers + Short-Term Financing Principal Due in Current Hawl + Accrued Salaries & Imminent Utilities
Net Zakatable Base = Gross Zakatable Assets − Deductible Commercial Liabilities
If your resulting Net Zakatable Base meets or exceeds the Nisab threshold on the maturity date of your Hawl, Zakat is due at the standard lunar rate of 2.50% (1/40). You can run this exact calculation automatically in our Universal Zakat on Business Assets & Commercial Wealth Calculator.
3. In-Depth Asset Ingestion: What to Include & How to Value It
A. Commercial Operating Cash & Bank Balances
All liquid currency held in physical cash registers, safe vaults, business checking accounts, and corporate deposit reserves must be added at 100% face value. This represents ready purchasing power.
B. Finished Inventory Valuation: Wholesale vs. Retail vs. Cost
One of the most frequent accounting dilemmas is determining the valuation basis of trade inventory on the maturity date (تَقْوِيمُ عُرُوضِ التِّجَارَةِ بِيَوْمِ الحَوْل).
- Retail Selling Price (Incorrect): Jurists strictly reject evaluating inventory at retail markup because future retail profits have not yet materialized and remain uncertain. Taxing unrealized future profits places an unjust burden on the business owner.
- Original Historical Purchase Cost (Incorrect): Historical cost does not reflect the current market purchasing power of the assets at the time the Zakat obligation matures.
- Current Wholesale / Net Realizable Replacement Value (Consensus): The contemporary consensus (AAOIFI Standard 35, Islamic Fiqh Academy of the OIC, and the majority of Hanbali and Hanafi scholars) affirms that merchandise must be valued at what it would cost to liquidate or replenish immediately in wholesale quantities on that exact date.
C. Obsolete, Damaged, and Stagnant Stock (البضاعة الكاسدة)
If goods have deteriorated, expired, or become obsolete such that they cannot be sold at normal wholesale prices, they must be marked down to their liquidation scrap value. If an item has zero resale demand and cannot be liquidated, its zakatable value is 0 until cash is realized.
D. Raw Materials & Work-in-Progress (WIP)
In manufacturing enterprises, raw materials that will be physically incorporated into the finished products for sale (such as fabric for clothing or lumber for furniture) are zakatable at replacement wholesale cost. However, auxiliary production fuels, lubricating oils, and testing chemicals consumed during manufacturing are exempt.
E. Accounts Receivable: Good Debts vs. Doubtful Debts (ديون مرجوة وغير مرجوة)
Trade debtors must be strictly categorized based on recoverability:
- Good Receivables (دين مرجو الأداء): Invoices owed by solvent clients who acknowledge the debt. These must be added to your current year’s zakatable base because they are functionally equivalent to liquid funds.
- Bad or Doubtful Receivables (دين غير مرجو الأداء): Invoices owed by bankrupt, insolent, or non-responsive debtors. These are excluded from your current zakatable assets. If collected in a future year, Zakat is paid for one year only upon receipt.
4. Strictly Exempt Fixed Capital: The Fiqh Principle of Qunyah (عروض القنية)
A widespread mistake made by commercial auditors is mistakenly including fixed capital assets in the Zakat calculation. In Islamic commercial law, items acquired for operational utility rather than commercial resale are designated as Qunyah and are 100% universally exempt from Zakat.
| Category | Status | Fiqh Rationale & Treatment |
|---|---|---|
| Finished Goods for Sale | Zakatable | Purchased with intention of trade (نية التجارة). Value at current wholesale price. |
| Industrial Plant & Machinery | 100% Exempt | Tools of production (آلات الصنع). Zakat is only paid on net liquid profits generated. |
| Commercial Real Estate & Factories | 100% Exempt | Operational premises are capital assets; only surplus rental income or revenues are taxed. |
| Delivery Vans, Trucks & Vehicles | 100% Exempt | Logistics and service utilities not intended for resale. |
| Computers, Software & Furniture | 100% Exempt | Office infrastructure and operational tools. |
When you audit your balance sheet in the RiazHub Commercial Wealth Calculator, our engine provides a built-in safety gate that automatically filters out all exempt fixed assets.
5. Deductible Commercial Liabilities: What Can You Subtract?
Classical scholars (such as Imam Al-Kasani in Bada’i al-Sana’i and Ibn Qudamah in Al-Mughni) affirm that immediate debts offset current zakatable wealth because the creditor holds a prior claim against those working assets.
However, AAOIFI Shari’ah Standard No. 35 draws a vital distinction between immediate short-term liabilities and long-term financing:
- Allowable Deductions: Accounts payable to suppliers, immediate operational expenses (due employee salaries, impending utility bills, warehouse rent due now), and the principal installments of loans due within the current fiscal Hawl.
- Disallowed Deductions: Long-term loan principal balances maturing 5, 10, or 20 years into the future. Subtracting multi-year capital loans from current inventory would artificially erase working capital Zakat entirely, which contravenes Shari’ah objectives (مقاصد الشريعة).
6. Dual Calendar Accounting: Hijri Lunar Year vs. Solar Fiscal Year
In classical Islamic law, the Hawl is calculated according to the Hijri Lunar Calendar (354 days) at the standard rate of 2.50% (1/40).
Nevertheless, the vast majority of modern commercial enterprises maintain their books on the Gregorian Solar Calendar (365 days). Because the solar year is approximately 11 days longer than the lunar year, applying a flat 2.50% to a solar fiscal year deprives eligible beneficiaries of 11 days of Zakat.
To resolve this disparity, AAOIFI Shari’ah Standard 35 established the mathematically reconciled rate:
$$\text{Solar Zakat Rate} = 2.50\% \times \frac{365.25 \text{ days}}{354.36 \text{ days}} \approx \mathbf{2.577\%}$$
When using the RiazHub Zakat on Business Assets Studio, you can switch between 🌙 Lunar (2.50%) and ☀️ Solar (2.577%) with a single click to ensure complete mathematical and Shari’ah compliance.
7. Determining Nisab: Silver Standard vs. Gold Standard
Nisab is the minimum threshold of net commercial wealth an enterprise must possess before Zakat becomes obligatory:
- Silver Nisab (595 grams of pure silver): The classical Jumhur standard recommended by the majority of contemporary jurists for cash and commercial goods, as it creates an accessible threshold that maximally benefits the poor (حظ الفقراء).
- Gold Nisab (85 grams of pure gold): Preferred by some contemporary scholars due to the historical erosion of silver’s relative purchasing power.
Our online calculator provides dynamic real-time benchmarks across all global currencies (including SAR, USD, AED, PKR, INR, GBP, EUR, and CAD) with customizable metal prices per gram.
8. Practical Walkthrough: A Modern Retail Enterprise Case Study
To observe how these rulings coalesce in practice, consider Al-Noor Trading LLC, a retail apparel distributor preparing its annual Zakat audit on the Gregorian fiscal year (Solar rate: 2.577%):
Al-Noor Trading LLC — Balance Sheet Audit
- Operating Cash in Corporate Accounts: $60,000
- Finished Garments (Current Wholesale Replacement Value): $180,000
- Raw Packaging & Unfinished Garments for Sale: $25,000
- Good Accounts Receivable (Solvent Invoices): $35,000
- Factory Building & Delivery Vans: $320,000 (100% EXEMPT — Qunyah)
- Total Gross Zakatable Commercial Assets: $300,000
- Trade Payables Owed to Textile Mills: $45,000
- Immediate Commercial Loan Installment (Due this year): $15,000
- Outstanding Staff Wages & Utility Bills: $10,000
- Total Deductible Commercial Liabilities: $70,000
Net Zakatable Working Capital Base: $300,000 − $70,000 = $230,000
Applicable Solar Rate: 2.577%
Total Enterprise Zakat Obligation: $230,000 × 0.02577 = $5,927.10 USD
If Al-Noor Trading has three equity partners (Partner A: 50%, Partner B: 30%, Partner C: 20%), the Zakat liability is apportioned directly by equity:
- Partner A (50%): $2,963.55
- Partner B (30%): $1,778.13
- Partner C (20%): $1,185.42
9. How to Handle Multi-Partner Partnerships & Corporate Shareholdings
Under modern commercial structures (Musharakah partnerships, Mudarabah ventures, LLCs, and joint-stock corporations), who is responsible for paying Zakat?
- Entity-Level Payment: If authorized by corporate bylaws, shareholder resolutions, or national law (such as ZATCA in Saudi Arabia), the company computes and dispenses Zakat directly on behalf of all owners before distributing dividends.
- Individual Shareholder Apportionment: If the corporation does not pay Zakat at the entity level, management must provide an audited working capital statement so each shareholder can pay Zakat proportional to their ownership percentage.
The RiazHub Commercial Zakat Studio includes an interactive Partner Equity Table that computes and prints exact individual liabilities for each director or partner.
10. Frequently Asked Questions (FAQ)
Q1: How do dropshipping and print-on-demand businesses calculate Zakat?
In dropshipping models, the merchant generally does not hold physical warehouse inventory. Therefore, Zakat is assessed primarily on liquid cash reserves in bank/payment gateway accounts (Stripe, PayPal, Shopify balance), goods in transit for which legal title has transferred, and good trade receivables, minus immediate supplier debts.
Q2: What if my business incurred an accounting net loss this year?
Zakat is levied upon accumulated working capital (الأصول المتداولة), not on annual net income or profitability. Even if an enterprise incurred an operational net loss for the year, if its remaining net working assets (cash + inventory + good receivables − current liabilities) exceed Nisab on the Hawl date, Zakat remains obligatory.
Q3: Can I deduct long-term real estate or vehicle loans?
No. Under AAOIFI Standard 35, only loan installments due within the immediate Hawl are deductible. Multi-year loan balances finance exempt fixed assets and cannot be deducted against current trading stock.
Q4: Is my confidential corporate financial data safe when using the calculator?
Yes, 100%. The RiazHub Universal Business Zakat Calculator processes all asset multiplications, debt subtractions, and canvas statement generation entirely inside your web browser using client-side JavaScript. No commercial figures, balances, or IP addresses are ever sent to an external server.
Conclusion & Next Steps
Accurately computing Zakat on trade merchandise is both an act of spiritual devotion and a hallmark of professional Islamic commercial governance. By adhering strictly to the wholesale replacement valuation rule, respecting the universal exemption of fixed production tools, and properly deducting short-term commercial debts, business owners can purify their commercial wealth with total peace of mind.
Ready to audit your enterprise balance sheet? Visit the Universal Zakat on Business Assets & Commercial Wealth Calculator on RiazHub to compute your obligation, generate export receipts, and download your formal Shari’ah audit statement card today.
Universal Zakat on Business Assets Studio
Compute auditable Zakat on commercial inventory, raw materials, liquid operating funds, and accounts receivable adhering strictly to classical jurisprudence (Hanafi, Shafi'i, Maliki, Hanbali) and the Net Working Capital Method (طريقة صافي الأصول المتداولة).
 SAR - Saudi Riyal (﷼)
| Commercial Asset / Debt Item | Amount (SAR) |
|---|---|
| Operating Cash & Bank Deposits | 0.00 |
| Finished Goods Inventory (Wholesale Valuation) | 0.00 |
| Raw Materials & Trading Work-in-Progress | 0.00 |
| Solvent Trade Debtors (Good Receivables) | 0.00 |
| Prepaid Operational Expenses & In-Transit Goods | 0.00 |
| [A] Total Gross Zakatable Commercial Assets | 0.00 |
| Less: Accounts Payable (Suppliers) | (0.00) |
| Less: Short-Term Debt Installments (Due in Hawl) | (0.00) |
| Less: Due Employee Wages & Imminent Utility Bills | (0.00) |
| [B] Total Deductible Commercial Liabilities | (0.00) |
| [A - B] Net Zakatable Working Capital Base | 0.00 |
| Active Nisab Threshold (Silver / Gold Benchmark) | 0.00 |
| Total Enterprise Zakat Obligation الزكاة الكلية | 0.00 |
| Your Apportioned Share (100% Equity) | 0.00 |
Apportion Zakat liability among multiple partners, directors, or shareholders according to each partner's capital contribution or equity share (حِصَص الشُّرَكَاء في رَأْسِ المَال).
| Partner / Shareholder Name | Equity Share (%) | Zakat Liability (SAR) | Action |
|---|
1. Wholesale / Market Replacement Valuation (القيمة الاستبدالية)
By consensus of contemporary Islamic jurisprudence councils (AAOIFI Standard No. 35, Islamic Fiqh Academy of the OIC), retail trade merchandise is evaluated at its current wholesale replacement cost on the date Zakat is due, NOT at the historical purchase price, and NOT at the anticipated retail selling price (as unrealized markup is not yet earned).
2. Obsolete, Stagnant & Dead Stock (البضاعة الكاسدة)
Items that cannot sell at wholesale must be marked down to their liquidation salvage value. If an item has zero resale demand, its value is 0 until sold.
3. Goods in Transit & Dropshipping (البضائع في الطريق)
If payment has cleared and the seller has completed delivery to the carrier (FOB Shipping Point), legal title has transferred, and the goods must be included in your commercial assets. If shipped on consignment, the consignor (owner) remains liable for Zakat.
4. Good Receivables vs. Bad/Doubtful Debts (ديون مرجوة وغير مرجوة)
Debts acknowledged by solvent clients (مرجوة) are treated like ready cash and taxed annually. Doubtful debts (debts of insolvent or non-responsive debtors) are excluded from the Hawl; when collected in the future, Zakat is paid for only one year upon receipt.
Jurisprudential Foundations of Zakat on Business Assets (عروض التجارة)
📜 Quranic & Prophetic Evidence
Allah commands in the Quran: "O you who have believed, spend from the good things which you have earned" (Surah Al-Baqarah 2:267). Mujahid narrated that this verse was revealed specifically concerning trade merchandise. Furthermore, Abu Dawud recorded from Samurah ibn Jundub (رضي الله عنه): "The Messenger of Allah ﷺ used to command us to pay Zakat from that which we prepared for sale."
⚖️ Deductibility of Commercial Liabilities
Under classical Fiqh (Al-Kasani in Bada'i al-Sana'i, Ibn Qudamah in Al-Mughni) and AAOIFI Standard 35, debts immediately due to suppliers or operational staff within the current Hawl are deducted because they offset working assets. However, long-term financing debts spanning multi-year tenures cannot be subtracted in their entirety to erase current working capital Zakat.
🌙 Lunar vs. Solar Accounting Reconciliation
The classical Shari'ah rate is 2.50% (1/40) based on a 354-day lunar Hijri year. For corporations operating under the Gregorian 365-day solar fiscal calendar, AAOIFI stipulates the mathematically reconciled rate of 2.577% (2.5% × 365 / 354) to ensure the 11-day calendar variance is equitably fulfilled.
🔒 100% Client-Side Privacy Guarantee
Your enterprise financial numbers, inventory valuations, bank balances, and partner details are executed 100% inside your web browser using client-side JavaScript. No balance sheet figures or sensitive commercial data are ever transmitted to or stored on our servers.