Master Your Retirement Wealth: Universal 401(k) Calculator, Employer Match Optimizer & SECURE 2.0 Studio
Introduction: The New Era of Retirement Planning Under SECURE 2.0
For decades, navigating a 401(k) plan seemed straightforward: contribute enough to capture your company’s match, select a broad-market index fund, and let compound interest perform its long-term magic. However, the modern financial landscape and significant legislative overhauls most notably the SECURE 2.0 Act have reshaped employee retirement economics.
Between increased statutory contribution ceilings, new tiered “super catch-up” rules for workers in their early sixties, mandatory Roth rules for high-earning catch-up contributors, and inflation eating away at nominal dollars, relying on rudimentary retirement calculators often leads to dangerous blind spots.
To eliminate the guesswork and empower working professionals, pre-retirees, and financial planners, RiazHub developed the Universal 401(k) Retirement Calculator & SECURE 2.0 Studio. Operating 100% client-side with zero data transmission or server logging, this studio provides institutional-grade retirement projections directly in your browser.
Why Most 401(k) Calculators Fall Short
Standard online retirement calculators typically suffer from three major design flaws:
- Static statutory caps: They ignore age-based catch-up increases and the SECURE 2.0 special windows.
- Oversimplified matching rules: They cannot handle multi-tiered corporate matches (e.g., 100% on the first 3% plus 50% on the next 2%).
- Nominal dollar illusions: They display large multimillion-dollar balances at retirement age without discounting for inflation, obscuring what that capital will actually buy in future grocery store dollars.
With the 401(k) Retirement Calculator Studio, every variable from annual salary inflation merit raises to expense ratio drag and real purchasing power discounting is modeled in discrete annual cash flows.
Core Features of the SECURE 2.0 Retirement Studio
1. 🏛️ Complete Statutory IRS & SECURE 2.0 Compliance Architecture
The calculation engine incorporates all current IRS Section 401(a)/(k) and IRC Section 415 statutory guardrails:
- Base Employee Deferral Limit: Statutory annual base ceiling of $24,500 for participants under age 50.
- Standard Age 50+ Catch-Up Deferral: Additional $8,000 allowable for participants aged 50–59 and 64+ (bringing max employee deferral to $32,500).
- SECURE 2.0 “Super Catch-Up” (Ages 60–63): A dedicated statutory window created under Section 109 of SECURE 2.0 allowing up to $11,250 in catch-up contributions (max employee deferral of $35,750).
- IRC § 415(c) Total Additions Cap: Enforces the comprehensive $72,000 aggregate limit on combined employee contributions, employer matches, and profit-sharing allocations.
- Annual Compensation Cap (IRC § 401(a)(17)): Automatically caps eligible compensation at $360,000 to guarantee statutory accuracy for high-income earners.
- FICA High-Earner Mandate Tracking: Dynamically flags workers earning over $150,000 in prior-year FICA wages who are mandated under SECURE 2.0 Section 603 to designate all catch-up contributions as after-tax Roth.
2. 🤝 Multi-Tier Employer Match & “Free Money” Optimizer
An employer match is an immediate 50% to 100% guaranteed return on your investment. Leaving match money unclaimed is identical to forfeiting earned compensation. The Universal 401(k) Calculator features an active Match Efficiency Engine that evaluates your contribution rate against standard and custom corporate formulas:
50% Match up to 6% of Pay(Standard corporate scheme)100% Dollar-for-Dollar up to 4% of PayTiered: 100% on first 3% + 50% on next 2%100% Match up to 6% of Pay(Generous corporate scheme)Custom Match % and Salary Cap
If your employee contribution rate falls below the match threshold, the tool instantly issues an alert calculating exact annual dollars forfeited and provides a 1-click button to maximize your match.
3. 📈 Interactive HTML5 Stacked Area Wealth Visualizer
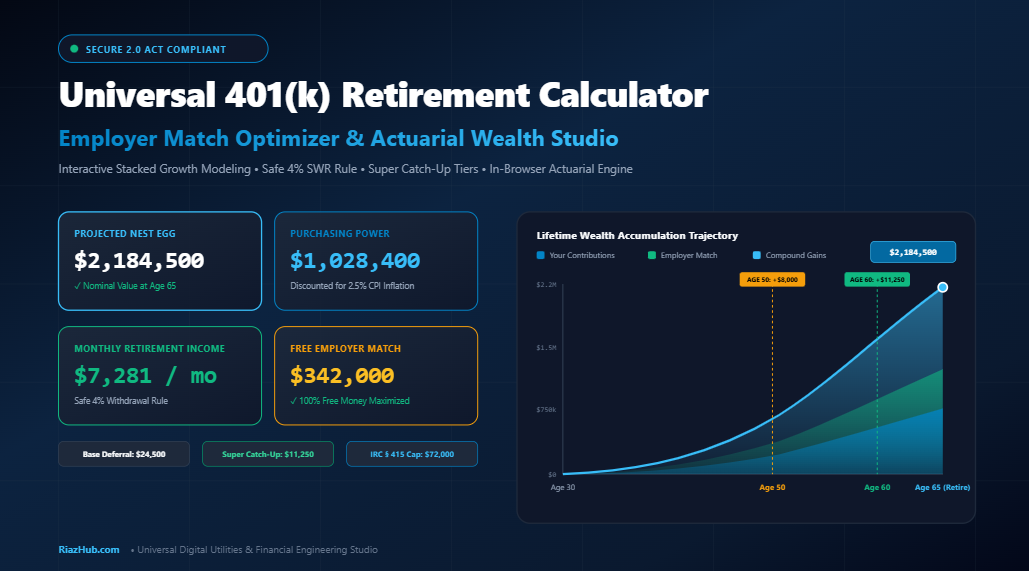
Visualizing where your future wealth originates is critical for long-term motivation. The built-in responsive canvas plots three distinct, color-coded stacked trajectories:
- Technical Azure Layer: Cumulative principal contributed from your paychecks.
- Emerald Green Layer: Cumulative free employer matching funds captured.
- Vibrant Cyan Layer: Cumulative compound investment returns.
The canvas includes interactive crosshairs displaying your exact balance breakdown year-by-year, along with vertical milestone markers at Age 50, Age 60 (super catch-up), and your target retirement age.
4. ⚖️ Traditional Pre-Tax vs. Roth Post-Tax Matrix
Unsure whether to take the immediate tax deduction or build tax-free retirement wealth? The tool models your estimated marginal income tax bracket today against expected retirement taxes, computing immediate annual tax savings with a Traditional 401(k) versus long-term tax exemption with a Roth 401(k).
5. 🛡️ Bengen Safe Withdrawal Rate (SWR) & Decumulation
Accumulating a nest egg is only half the battle; knowing how much you can safely withdraw without outliving your portfolio is paramount. The studio calculates your sustainable monthly retirement drawdown using the standard 4% Safe Withdrawal Rule, providing both nominal monthly figures and inflation-discounted purchasing power equivalents.
6. 🖼️ Executive Wealth Dossier Card Canvas (1200×630)
Generate high-resolution social and executive certificates summarizing your retirement projection, employer match efficiency, and sustainable monthly drawdown. Built with zero third-party image servers, the canvas auto-adapts to your viewing mode and allows instant 1-click PNG downloads.
Step-by-Step: How to Project Your 401(k) Wealth
Modeling your complete career trajectory on the RiazHub 401(k) Retirement Studio takes just moments:
- Define Your Horizon: Enter your current age, target retirement age, current annual salary, existing 401(k) balance, and projected annual wage raises.
- Set Contribution Rate & Tax Treatment: Choose your employee deferral percentage (1% to 50%) and select between Traditional Pre-Tax or Roth Post-Tax.
- Configure Company Match: Pick your employer’s matching formula. Verify whether the match efficiency badge confirms you are capturing 100% of available employer funds.
- Calibrate Market Assumptions: Adjust your expected annual investment return (e.g., Conservative 5%, Moderate 7%, or Aggressive 9%), expected CPI inflation, and investment fund expense ratios.
- Analyze the Results: Explore the Interactive Stacked Canvas, examine the Career Ledger with real inflation toggles, download your 1200×630 Retirement Dossier, or export the entire annual schedule as a CSV spreadsheet.
Actuarial Comparison: The Cost of Missing the Employer Match
Consider an employee earning $85,000 per year whose employer offers a 50% match on contributions up to 6% of pay:
| Scenario | Employee Contrib. Rate | Annual Match Received | Match Lost per Year | 30-Year Opportunity Cost (@ 7%) |
|---|---|---|---|---|
| Sub-Optimal (3% Contrib.) | $2,550 (3%) | $1,275 | -$1,275 / yr | ~$129,000 lost |
| Full Match (6% Contrib.) | $5,100 (6%) | $2,550 | $0 (100% Captured) | +$258,000 gained |
By bumping contributions from 3% to 6%, the employee secures an extra $1,275 annually in pure employer funding, which compounds to over $129,000 in additional wealth over three decades. Test your exact salary numbers now on the Employer Match Optimizer.
Frequently Asked Questions (FAQ)
How does the SECURE 2.0 “Super Catch-Up” work?
Under Section 109 of the SECURE 2.0 Act, active participants aged 60, 61, 62, and 63 are eligible for a higher catch-up contribution limit of $11,250 (or 150% of the standard catch-up limit). For individuals outside this age window who are 50 or older, the standard $8,000 catch-up applies.
What is the FICA $150,000 high-earner Roth rule?
SECURE 2.0 Section 603 mandates that employees whose prior-year Social Security (FICA) wages exceeded $150,000 (indexed for inflation) cannot make catch-up contributions on a pre-tax basis. Instead, their catch-up deferrals must be directed into a Roth (after-tax) account.
Does this tool store or transmit my financial data?
No. The Universal 401(k) Retirement Calculator operates with 100% zero-telemetry client-side JavaScript. All compounding calculations, ledger projections, and dossier cards are rendered entirely inside your browser sandbox.
Conclusion: Take Charge of Your Financial Independence
Retirement readiness is not a lottery—it is an engineering discipline. Understanding how compound investment gains, employer match optimization, statutory tax limits, and inflation discounting interact allows you to make informed decisions that accelerate your path to financial freedom.
Experience the future of personal wealth forecasting today with the Universal 401(k) Retirement Calculator, Employer Match Optimizer & SECURE 2.0 Studio on RiazHub.
Universal 401(k) Retirement Calculator & SECURE 2.0 Studio
Model compound wealth trajectories, optimize tiered company match contributions, evaluate SECURE 2.0 super catch-up limits, and project sustainable monthly retirement drawdowns with 100% browser-based actuarial precision.
👤 1. Career Baseline & Horizon
💵 2. Contributions & Tax Mode
🤝 3. Employer Company Match
📊 4. Returns, Inflation & Fees
| Age | Salary | Employee | Match | Gains | End Balance |
|---|
Statutory Disclaimer: This utility tool is designed solely for hypothetical educational and wealth projection purposes in compliance with general IRS § 401(k) guidelines. It does not constitute individualized investment, actuarial, legal, or tax advice. Market returns fluctuate, and past performance does not guarantee future results. Consult a licensed CERTIFIED FINANCIAL PLANNER™ (CFP®) or CPA before making significant financial commitments.